Open web. Clear feed.

Asymmetric Stock Ideas + MEMES. Not Advice. Lately a lot of scorecards on prints, for all you lazy bastards
$SNAP BEST IN CLASS AT ISSUING WORTHLESS EQUITY
Congratulations to snapchat who now holds the rare trifecta - Down 90% from peak - Cumulative SBC equal to 2x the current market cap - Not a single insider buy in company history

$NVDA if they had not raised, stock would be -10%, if they had derisked stock would be $100-120, but the band aid would have been ripped off and been easier to buy. feels like no mans land. too much uncertainty left. that 10Q filing is now like another earnings release, coming any day (or in a few weeks?)
$NVDA SIG Flash, Reiterates $275 PT NVIDIA once again delivered significantly better results and guidance, beating our prior 3Q and 4Q estimates by an impressive ~$6.5B and ~$5B, respectively. That said, revenues in the quarter included ~$2.4B of Hopper sales to China that were not previously included in the company’s CY3Q guidance. Additionally, there was a 14th week to be included in the fourth quarter. More importantly though, NVIDIA once again increased its guidance for FY28. Namely, the company now expects to grow 75% YOY (and on a higher base given the stronger 4Q guide), implying ~$40B of upside. To meet its outsized growth expectations, the company increased its supply commitment by roughly ~$110B (now ~$390B), with investments mostly centered on securing additional HBM capacity. Turning to CY3Q, Hyperscale results were ~$8B better than our expectations, offsetting -$2 billion weaker results in ACIE (interestingly, Hyperscale outgrew ACIE, contrary to the company’s guidance). The early ramp of Rubin also contributed to the better results as sales here ramped to ~ $20B in a single quarter (although this was a tad less than we had expected). Meanwhile, Blackwell Ultra also grew sequentially in CY3Q. Promisingly, the company broadly reaffirmed its roadmap over the coming years, spanning CPO scale out (2H26), Rubin Ultra next year (2027), and Feynman (2028). Despite current market skepticism around the sustainability of AI investments, neocloud financing, and access to LPS, interim CEO Colette Kress seemed to broadly reiterate the company’s views under the Jensen regime. As a testament to the inflection in demand that the company is seeing, management noted that B300 cloud pricing had increased by ~60% QOQ in 3Q (we called out a doubling in spot pricing for B300 in our 3Q26 AI-SIGnals note here). Beyond the top line, gross margins were 90 bps better than we had expected, though the better results may have been due to the shipment of previously written-down Hopper SKUs into China. CY4Q GMs were guided to decline 340bps due to the ramp of the Vera Rubin platform, roughly in line with our prior expectations. In all, this was a much-needed positive report that may assuage investors amid the ongoing upheaval in the AI industry. That said, concern about LPS availability and financing in 2028 and beyond are unlikely to fully wind down. We reiterate our Positive rating and $275 price target (~16.5x C2027E EV/NOPAT).


$NVDA was $162 monday at the close, if the stock is red tomorrow, after that beat and raise and big "we got this" then the new CEO made a mistake. should have taken the free putt to cut the guidance and derisk the model (even if they can beat it) wall street is all about under promise and over deliver, especially when u are new and calling the shots at the #1 co in the world. $NVDA now under $157. I wonder if Joe Moore will raise his FY 28 revs back up from low 50% growth to 75%, if he does, he screwed up too, keep the bar low, so u stay in good graces of the new "dream team"

$NVDA i still dont understand the logic in this, the stock is down from $240 to $160, almost 100 pts, they are giving u a free pass to take down the bar, instead you raise the bar, if you are not going to get paid to gun it, why do it. just focus on execution, and keep beating the numbers that are out there. certainly the risk to guidance is going UP not down, given the swirling vortex that $nvda has entered. seems like a mistake. I am actually sorta shocked by it. unless you can grow 80-85-90% why raise?

$NVDA the big debate tomorrow, if the stock closes RED, the market wanted DE RISKED GUDIANCE, and the new CEO messed up and painted herself further into a corner even with a dropping stock. or, if she really does have it like that, and they are gonna jack guidance all year long because demand is THAT good, then $NVDA is gonna put some bears in a body bag. All i know is, eventually, the market gets what the market wants. and in this event driven cluster fuck, the market wants derisked guidance at $NVDA and they want @JensenHuang back as CEO. because they dont trust the others to deliver the big beats
CYBER ATTACKS.
I hold no Nvidia stock, and I publicly opposed both the Iran War and tariffs. I'm an extreme bear on the S&P and US markets in general. I don't do any TACO trading b/c I am a long-term investor, not a trader. And I don't think the AI capex is long term sustainable. But I do support open weight models, and the free Internet, and Jensen was a champion of that. I also oppose the cancellation of an innocent man over manufactured lies about "Chinese spies" mixed in with (let's be honest) at least some anti-Asian bias. Jensen didn't get the benefit of the doubt due to his ethnicity. Finally, regarding the AI issue, below are the graphs I'm referencing. In case you aren't aware, there is a cybersecurity event happening. There absolutely will be a large defense allocation globally towards AI tokens to find vulnerabilities before they're hacked. And there's no question that Nvidia chips will be used to power that AI inference. Therefore, there's zero cargo cult here. The second graph alone shows a direct relationship between tokens (and hence chips) and cyberdefense. Obviously, Jensen can help there.

$NVDA i still dont understand the logic in this, the stock is down from $240 to $160, almost 100 pts, they are giving u a free pass to take down the bar, instead you raise the bar, if you are not going to get paid to gun it, why do it. just focus on execution, and keep beating the numbers that are out there. certainly the risk to guidance is going UP not down, given the swirling vortex that $nvda has entered. seems like a mistake. I am actually sorta shocked by it. unless you can grow 80-85-90% why raise?
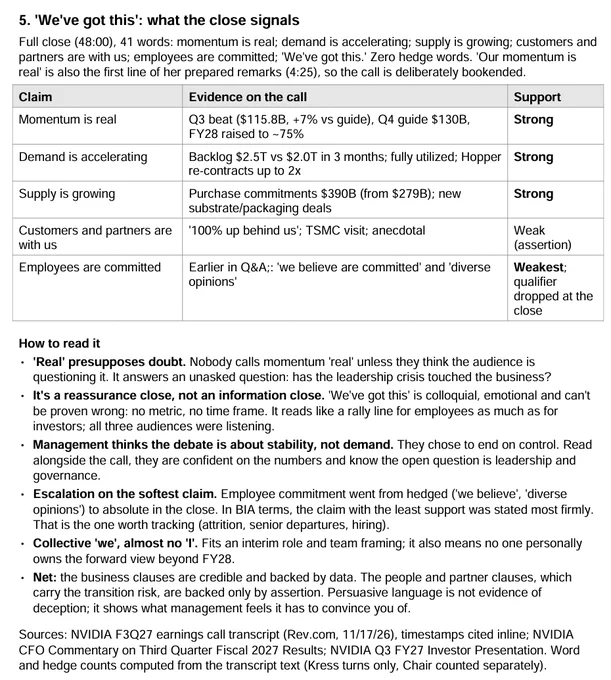
$NVDA "WEVE GOT THIS" FOR THE CLOSE 'Real' presupposes doubt. Nobody calls momentum 'real' unless they think the audience is questioning it. It answers an unasked question: has the leadership crisis touched the business? It's a reassurance close, not an information close. 'We've got this' is colloquial, emotional and can't be proven wrong: no metric, no time frame. It reads like a rally line for employees as much as for investors; all three audiences were listening. Management thinks the debate is about stability, not demand. They chose to end on control. Read alongside the call, they are confident on the numbers and know the open question is leadership and governance. Escalation on the softest claim. Employee commitment went from hedged ('we believe', 'diverse opinions') to absolute in the close. In BIA terms, the claim with the least support was stated most firmly. That is the one worth tracking (attrition, senior departures, hiring). Collective 'we', almost no 'I'. Fits an interim role and team framing; it also means no one personally owns the forward view beyond FY28. Net: the business clauses are credible and backed by data. The people and partner clauses, which carry the transition risk, are backed only by assertion. Persuasive language is not evidence of deception; it shows what management feels it has to convince you of.