One nerd’s perspective on the financial planning world… CFP, #LifelongLearner, Entrepreneur-In-Denial, Advisor #FinTech, & publisher of the Nerd’s Eye View blog
Our list of "Best Conferences 2025!", and be sure to take advantage of the discount codes that several have offered to Nerd's Eye View readers!
Best in:
-Overall Planning: @FPANorCal
-Technology: @t3techhub
-Advanced Tax Planning: @AICPA Engage
and more!
bit.ly/4fisUpb
As AI-enabled technology begins to percolate, firms are finding themselves with a tempting solution: Simply outsource every possible entry-level task to an AI agent. And why not? Agents don't need much mentorship or guidance; they don't take PTO days or ask for a 401(k) match. However, it's a cure that risks becoming worse than the disease. kitc.es/4BZ60PU
In this guest post, Daniel Yerger, founder and owner of the RIA MY Wealth Planners, explores why firms should continue to invest in developing entry-level planners amidst the rise of AI, from the risks of relying on technology over talent, to the tasks and career path that make doing so worthwhile.
The question of automation vs. augmentation comes up whenever a new technology like AI disrupts a field. In some cases, a previously skilled job is automated away, decreasing the value of that particular labor. Which raises the practical but remarkably difficult question: how should we counsel clients through potential extreme outcomes? kitc.es/4kLP495
In this guest post, Zach Bennedsen, CFP, a Product Manager for Advisor360°, explores how advisors can think through the incredible breadth of upside and downside scenarios for AI, and the ways to have practical conversations with clients about how they can plan for and within an era of such uncertainty. #AI#advicers
The long-term value of a financial advisor beyond just security selection and portfolio management, and highlights a "hierarchy of financial advisor value" that starts with the areas where financial advisors have the most impact: kitc.es/4gCh4Kn#financialadvisor#advicers
In 2024, the typical three-member team collectively dedicated 22 hours per client across all team members during the first year of the relationship and 21 hours annually in subsequent years.
Total team hours per client tend to increase with revenue per client, as higher-revenue clients typically have more complex financial planning needs that require additional time to address. These growing service demands help explain why, beyond a certain point, teams begin serving fewer clients per advisor as revenue per client increases.
We dive deeper into how financial planners actually spend their time in our Advisor Productivity Study, available entirely for free here: kitc.es/4gpB6Ef
How @RubinJMiller uses a combination of synchronous and asynchronous communication throughout the year to efficiently deliver portfolio and planning reviews to his busy clientele, allowing Peltoma Capital to add $200 million in AUM and 70 clients in just the past three years. kitc.es/4sHP782
In this episode, we talk in-depth about how Rubin meets with clients for an annual meeting at the start of the year but then conducts a mid-year planning and portfolio update asynchronously using screen recording tool Loom, how Rubin has found that this cadence works well both for his clients and for his firm, and how Rubin has recognized the importance of each team member sticking to key due dates for their contribution to ensure that asynchronous products are produced in a timely manner. #FASuccess
The tipping point that leads to the need for more structure: As we grow, how do we balance firm efficiency with providing quality and value to the client? kitc.es/3Wzb7pH
In this guest post, Mike Lecours explores how advisors can use two kinds of Client Service Calendars (CSC), which isn't a one-size-fits-all solution, but rather a framework that can be pointed at whichever constraint is actually binding for the firm: capacity or perceived value:
-Efficiency-focused CSC, designed to streamline the advisor's workload by consolidating outreach into fewer, more systematized touchpoints
-Value-enhancement CSC, better suited to firms with capacity to spare, aimed at deepening the client relationship by pulling the advisor's 'behind the scenes' work
#advicers
Reg BI will grant – and in fact, require – that broker-dealers now explain their standard of conduct as being an obligation to act “in the best interests of the customer when making a recommendation.”
Which leaves little room for RIAs to market their fiduciary obligation to act “in the best interests of the client” as a differentiator when broker-dealers will be able to use substantively identical words. Raising the question: how will RIAs differentiate themselves in the future? kitc.es/4vmWaCG
Working as an associate advisor can come with frustrations based on the extent (and limits) of their job responsibilities and the freedom granted to them. For instance, because they have relatively less experience than lead advisors, their firm might not yet be confident in their ability to present 'live' in client meetings, as a mistake made by the associate in the meeting could reduce a prospect's or client's trust in the firm. kitc.es/4AgoBoU
The value of a spousal spending 'check-in number': One strategy for maintaining cash flow balance and marital harmony is to create a "check-in number" that represents the upper limit of how much each partner can spend on an individual purchase without checking in with the other.
(Heather & @dougboneparth | The Joint Account)
More curated articles #WeekendReading: kitc.es/4kkPmnv
IRS Updates Tax Brackets, Deductions, Credits For 2027 ➡️ The IRS recently issued 2027 inflation adjustments for tax brackets, the standard deduction, tax credits, and retirement account contribution limits, amongst other areas, providing advisors with an opportunity to ensure clients are maximizing opportunities and avoiding entering phase-out areas. kitc.es/4kkPmnv#WeekendReading@irs
Getting started as a financial planner is difficult. Financial planning still has quite a ways to go to create the sorts of clear career progression paths that exist in the fields of medicine, law, and accounting. 10 tips for new financial planners looking to maximize their own progression down the financial advisor career path: kitc.es/44Tmiu5
In the modified RMD approach, the average of the last three years of portfolio values is used to calculate the withdrawal, rather than the value on a single (arbitrary) day. The total portfolio value at a certain point, say December 31st, of each of the last three years is added together and divided by 3. This provides a rolling three-year (RTY) average value. This average value is divided by the appropriate divisor in the RMD table, which yields the following year's withdrawal amount. kitc.es/4t2XNVi#RMD
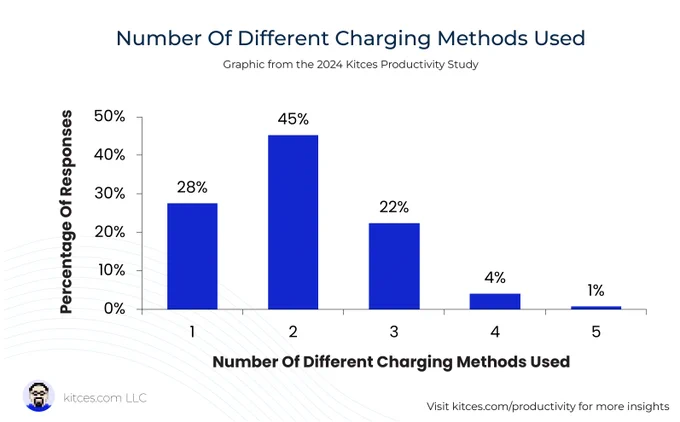
Most advisory teams use more than one way to charge for their services. Only 28% use just one pricing method, such as AUM-only or subscription-only. 45% rely on two (such as AUM plus commissions or AUM plus a subscription fee) and 27% use three or more.
We look at how advisors charge for their services in greater detail in our Advisor Productivity Study, available entirely for FREE here: kitc.es/4gpB6Ef
How can advisors deliver bad news to new clients? What do you say to this client that doesn't seem to understand or want to admit that their spending habits probably aren't going to work for their retirement, or it sounds like they're getting ready to retire and maybe should work more years than they want to. And they're hooked to another advisor who said they were going to be okay. kitc.es/3XfXID3
In this 203rd episode of Kitces & Carl, we discuss how to help a client who wants a retirement they can't afford – especially if their previous advisor has left them with the impression that they can afford that lifestyle.
The latest in #AdvisorTech: @orionwealthtech has announced a new fee on technology vendors that access Orion data via integration, forcing providers to decide whether to eat the fee, raise their own prices, or stop integrating with Orion.
Will other AdvisorTech platforms follow Orion's lead in charging vendor-level data access fees? Does a standalone AI 'operating system' offer something more than what's available in existing advisor software (that often wants to be the operating system itself)? Do AI tools reduce the value proposition for centralized data warehouse providers like @milemarkerco? kitc.es/4ix6zY9